For non-resident Indians navigating offshore wealth strategies, allocating capital back to the home country has historically involved structural friction. Traditional inbound channels often force global investors to absorb domestic currency depreciation, navigate complex non-repatriation clauses, and contend with double taxation challenges. The establishment of the Gujarat International Finance Tec-City as India’s premier International Financial Services Centre has fundamentally altered this dynamic. High-net-worth individuals and family offices now have a specialized jurisdictional gateway that operates under international financial regulatory standards while providing direct access to the domestic growth story.
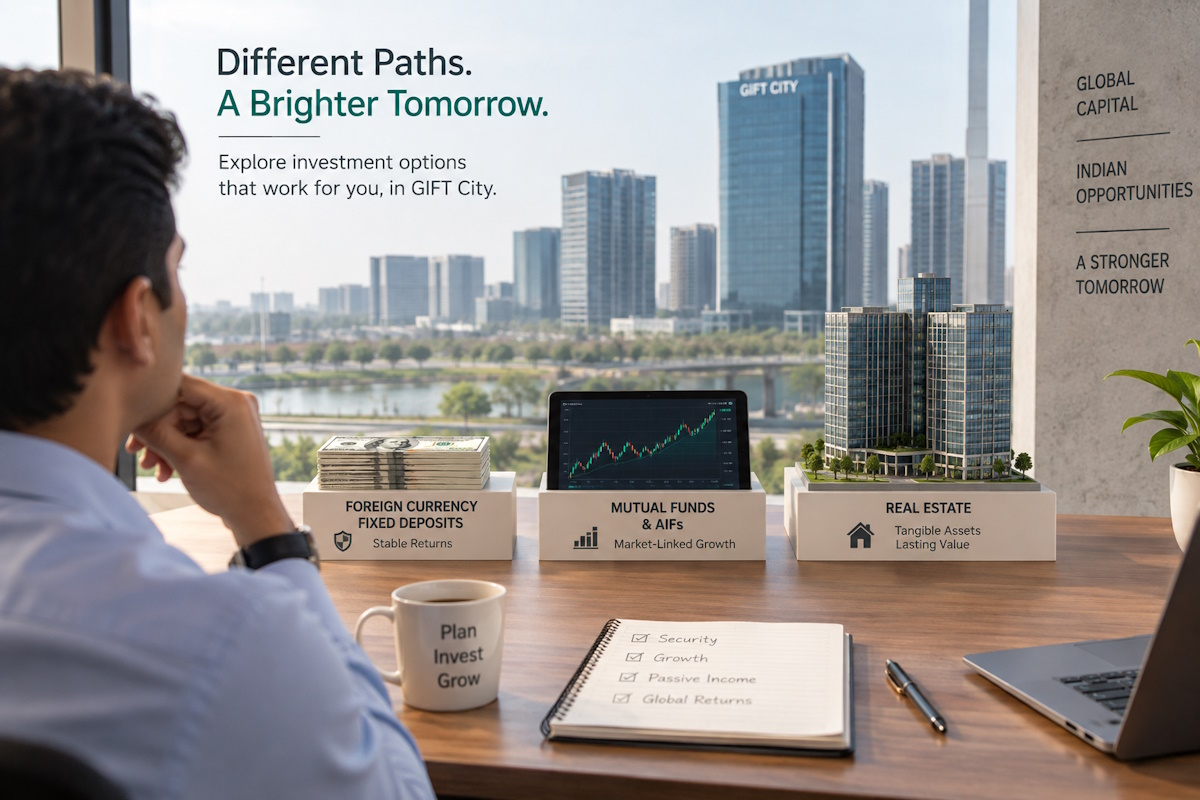
When you decide to invest in India through GIFT City, the primary decision does not stop at choosing the jurisdiction. The critical question shifts to vehicle selection. Wealth managers and private banks actively pitch three primary instruments: Foreign Currency Fixed Deposits, market-linked Mutual Funds or Alternative Investment Funds, and direct real estate assets across commercial or residential sectors. Each asset class solves a fundamentally different investment objective, presenting distinct trade-offs across liquidity, tax efficiency, capital appreciation, and currency exposure. Selecting the appropriate vehicle requires evaluating how regulatory benefits translate into net, post-tax dollar yields.
Evaluating Fixed Income: The Reality of GIFT City FDs for NRIs
Fixed income has traditionally served as the initial entry point for conservative NRI capital. Within the IFSC ecosystem, offshore banking units allow non-residents to establish Foreign Currency Term Deposits denominated in major global currencies such as USD, EUR, and GBP. These deposits function outside the traditional domestic banking regulatory framework, offering a completely distinct mechanism from standard NRE or NRO fixed deposits placed with mainland domestic branches.
Currency Denomination and Net Yield Profiles
The primary appeal of placing a fixed deposit through an IFSC banking unit in GIFT City is the total elimination of foreign exchange risk. When capital is held in US Dollars, the investor avoids the structural depreciation of the Indian Rupee against the Dollar, which historically averages two to three percent annually. An investor depositing funds does not have to worry about converting back to their home currency at an unfavorable exchange rate upon maturity.
However, this currency security comes with a direct yield trade-off. Foreign currency deposits in GIFT City track international benchmark rates such as the Secured Overnight Financing Rate rather than the higher nominal interest rates available in domestic Indian fixed deposits. While domestic NRE deposits might offer nominal yields between seven and eight percent in Rupee terms, IFSC Dollar deposits typically yield between four and five and a half percent depending on tenure and prevailing global monetary cycles. For investors seeking wealth accumulation rather than short-term capital preservation, fixed deposits rarely beat inflation over extended holding periods.
Taxation and Repatriation Mechanics
From a regulatory and compliance standpoint, foreign currency deposits in the IFSC maintain a distinct competitive edge. Under Section 10(4D) and related provisions of the Indian Income-tax Act, interest income earned on foreign currency deposits by non-residents in an IFSC Banking Unit is completely exempt from domestic income tax. There is no domestic withholding tax deducted at source, eliminating the administrative friction of claiming refunds or filing domestic annual tax returns purely for interest income.
Full repatriation is guaranteed because the capital remains in freely convertible foreign currency throughout the investment lifecycle. Investors seeking detailed operational clarity regarding foreign exchange guidelines often review our framework on NRI Investment in GIFT City to understand how offshore banking entities process international transfers without regulatory clearances from the central bank.
Key Allocation Caveat for Capital Preservation
While the mechanics are clean, fixed deposits in GIFT City remain an instrument for capital parking rather than strategic wealth expansion. The yield ceiling is fixed, capital appreciation is mathematically zero, and real yields can turn negative during prolonged periods of high global inflation. For an institutional or private portfolio, these deposits should strictly represent operational cash reserves or temporary liquidity tranches awaiting deployment into higher-yielding growth assets.
Market-Linked Returns: Mutual Funds and Alternative Investment Funds (AIFs)
Investors seeking capital appreciation combined with institutional management often look toward market-linked funds established within the IFSC. GIFT City has witnessed rapid regulatory liberalization under the International Financial Services Centres Authority, enabling domestic and global asset management companies to launch feeder funds, equity mutual funds, and private wealth vehicles directly within the international zone.
Inbound Investment Architecture and Feeder Funds
Choosing to invest in India through GIFT City via mutual funds or Category II and III AIFs allows non-residents to participate in public Indian equity markets through an offshore gateway. Capital is committed in US Dollars, converted into domestic assets by the fund manager, and repatriated back into foreign currency upon redemption. This structure provides a transparent route for global family offices that prefer passive portfolio administration rather than managing direct asset titles.
Specialized institutional funds operating inside the zone often deploy quantitative strategies, sector-specific debt structures, or broad-market large-cap index replication. For NRIs living in jurisdictions with strict reporting requirements, such as the United States or Canada, entering the Indian public markets through regulated IFSC fund managers can streamline regulatory filings. To compare how different allocation vehicles balance risk over long investment horizons, institutional clients frequently consult analytical tools such as our Real Estate Calculators to project comparative growth profiles against physical assets.
Management Expenses, Volatility, and Net Capital Gains
The market-linked route is not without measurable friction. Equity portfolios inherently expose capital to broad market volatility, geopolitical cycles, and sector rotation risks. In addition to market drawdowns, fee structures can materially compress cumulative compounding returns over time. Most offshore funds and AIFs registered in GIFT City levy annual management fees between one and two percent, accompanied by performance fees ranging from ten to twenty percent above a specified hurdle rate.
Taxation on capital gains represents another core strategic consideration. While GIFT City provides specific tax holidays for fund management entities, individual non-resident investors redeeming units in offshore equity funds are still exposed to capital gains tax rules depending on the fund’s underlying asset holding structure and applicable bilateral Double Taxation Avoidance Agreements. Unhedged currency movements between the Dollar and the Rupee within the fund’s underlying portfolio can also erode nominal gains during economic downturns.
Portfolio Volatility vs Stable Income Streams
Market-linked equities deliver capital growth during prolonged economic expansions, but they lack the contractual, predictable income profile demanded by many NRI investors. For non-residents entering mid-career retirement planning or family wealth distribution phases, public equity funds cannot replace the predictable quarterly distributions provided by real estate assets with corporate lease covenants.
Tangible Assets: Real Estate Investment Dynamics in GIFT City
Direct property acquisition represents the third and most structurally robust capital allocation pathway in the special zone. Unlike speculative land or broad suburban housing developments, real estate in GIFT City functions as an integral component of a master-planned, high-density financial district. The city is systematically divided into a Special Economic Zone, which serves as the offshore IFSC, and a Domestic Tariff Area, which supports mainstream business operations and executive urban living.
Commercial Real Estate Yields and Global Corporate Leasing
Commercial assets in GIFT City offer a structural advantage rarely seen in standard Indian metropolitan business districts. The ecosystem is explicitly designed to house global investment banks, multinational technology firms, insurance conglomerates, and aircraft leasing operations. These enterprises expand within the district due to substantial corporate tax exemptions, including a ten-year corporate tax holiday, zero minimum alternate tax, and subsidized operating environments.
As corporate giants scale their operations, commercial office leasing has experienced structural demand acceleration. Institutional landlords and commercial office investors achieve gross rental yields ranging from eight to ten percent in Grade-A commercial spaces, far outpacing the standard two to three percent yields typical of domestic Indian residential real estate, or the three to four percent yields found in gateway global cities like London, New York, or Singapore. Leases in modern GIFT City office towers often incorporate nine-year commitments with institutional-grade lock-ins and contracted escalations of twelve to fifteen percent every three years.
Residential Demand Driven by Executive Density
A critical divergence in GIFT City real estate lies between commercial absorption and the accompanying residential deficit. As major international financial institutions staff their middle and senior management desks inside the IFSC, the demand for walk-to-work housing within the processing zone and the adjacent domestic boundary has surged. Executive housing, modern studio configurations, and luxury high-rise apartments experience high occupancy rates driven directly by corporate professionals requiring immediate access to their trading desks and regional headquarters.
Residential properties in the district regularly generate rental yields between four and six percent, which is nearly double the average residential rental yield of neighboring metropolitan markets. When coupled with underlying capital appreciation driven by phased municipal infrastructure, transit lines, and international educational campuses, physical property delivers a dual-engine return profile consisting of contractual cash flow and long-term asset value appreciation.
Inflation-Hedged Cash Flow Architecture
Real estate serves as the definitive hedge against global monetary debasement. While a fixed deposit pays a fixed coupon that loses purchasing power, commercial real estate rents adjust upward through structured contractual escalations. Tangible real estate provides non-resident investors with direct title ownership under transparent regulatory oversight, eliminating intermediary management fees common in mutual funds.
Comparative Investment Evaluation: Yield, Risk, and Operational Control
Navigating the selection process requires isolating how each asset class performs under operational conditions. NRIs often commit capital based on headline interest rates without accounting for long-term purchasing power, liquidity bottlenecks, or foreign exchange taxation. Examining these vehicles side-by-side reveals their operational differences across an investor’s balance sheet.
Direct Multi-Asset Class Matrix
The operational contrasts across GIFT City asset classes demonstrate how real estate, funds, and fixed deposits cater to divergent investor risk tolerances:
- Gross Yield Generation: Foreign Currency FDs deliver between 4.0% and 5.5% in hard currency. Mutual funds and AIFs exhibit fluctuating market returns, ranging from negative territory in bear cycles to 12% to 15% in bull markets, but yield zero contractual liquidity. Real estate provides 8% to 10% gross yields in commercial segments and 4% to 6% in residential properties, backed by tenancy contracts.
- Capital Appreciation Potential: Fixed deposits deliver zero capital growth. Market funds participate directly in economic upside but carry downside volatility. Real estate benefits from expanding commercial density, with land supply restricted by master planning, driving baseline capital appreciation across project development cycles.
- Tax Treatment: Foreign currency FD interest within the IFSC is tax-exempt for NRIs. Mutual funds trigger capital gains taxation based on holding period and bilateral treaties. Real estate benefits from standard statutory deductions on rental income, depreciation write-offs where held through dedicated corporate entities, and indexation-based long-term capital gains treatments under domestic statutes.
- Liquidity and Exit Flexibility: FDs provide high liquidity, allowing early redemption subject to minor interest penalties. Mutual funds offer systematic redemptions, though Category II AIFs frequently feature strict five-to-seven-year lock-in periods. Real estate requires measured transactional marketing over two to four months to exit at market peak, making it an illiquid, wealth-compounding vehicle.
- Currency Inflation Protection: FDs shield the base principal from Rupee depreciation but do not protect against Dollar inflation. Mutual funds offer indirect inflation hedging through equity price expansion. Real estate provides direct inflation hedging, as replacement construction costs rise and lease contracts mandate periodic rent increases.
Investors interested in structuring real estate portfolios alongside fixed income allocations can reference our comprehensive analysis on NRI Investment in GIFT City to optimize holding structures.
Critical Mistakes Non-Resident Investors Make
One frequent mistake observed among global private clients looking to invest in India through GIFT City is treating these instruments as interchangeable. An investor seeking quarterly passive cash flow often buys equity mutual funds, only to face anxiety during inevitable public market corrections. Conversely, investors seeking rapid growth occasionally commit large capital sums to foreign currency fixed deposits, watching their net yields fail to outpace inflation in their country of residence.
Another major operational error involves purchasing residential real estate without verifying whether the asset sits in the SEZ or the Domestic Tariff Area. While SEZ residential properties cater directly to employees working within the IFSC, DTA properties enjoy a broader leasing pool that includes executives operating in the wider domestic region. Misunderstanding these regulatory zoning boundaries directly affects void periods and tenant turnover rates.
Strategic Investor Framework: Optimizing Your Capital Allocation
Sophisticated global investors rarely concentrate their entire asset base in a single instrument. The true benefit of GIFT City lies in its capacity to serve as a comprehensive wealth platform where an investor can build a balanced, multi-tier allocation strategy within one transparent regulatory environment.
The Balanced Portfolio Allocation Model
A resilient international allocation framework utilizes each instrument to satisfy a targeted liquidity and return mandate:
- Core Foundation (50% to 60% in Commercial or Residential Real Estate): Deployed into Grade-A office footprints or high-demand executive housing. This allocation anchors the portfolio with consistent rental income, protects against global inflation, and captures district-level capital appreciation.
- Growth Engine (25% to 35% in AIFs or Equity Funds): Deployed into curated public market funds or pre-IPO venture vehicles to participate in India’s expanding industrial and financial growth sectors.
- Liquidity Buffer (10% to 15% in Foreign Currency Fixed Deposits): Maintained in USD deposits inside an IFSC Banking Unit to meet immediate overseas capital calls, service property acquisition milestones, or execute opportunistically during broader market corrections.
By reviewing analytical tools like our Real Estate Calculators, private investors can quantify the compounding effect of combining stable real estate yields with opportunistic liquid allocations.
Making the Definitive Allocation Call
If your investment goal centers on low-volatility preservation of foreign currency reserves without tax friction, GIFT City foreign currency fixed deposits are functional tools. If you prioritize growth, accept volatility, and wish to outsource stock picking to institutional asset managers, regulated offshore mutual funds and AIFs provide clean market access.
However, if your primary investment objective is securing strong, inflation-protected cash flow paired with tangible asset security, real estate remains the premier investment asset class in GIFT City. The district’s rapid corporate absorption, infrastructure backing, and tenant profile provide an institutional property ecosystem that delivers long-term returns for private wealth portfolios.
Frequently Asked Questions
1. Can an NRI repatriate sales proceeds from GIFT City real estate without regulatory friction?
Yes. Non-resident investors purchasing properties through foreign currency banking routes or authorized inward remittances can repatriate their capital and accumulated capital gains under clear RBI and FEMA guidelines, provided all applicable local capital gains taxes have been settled.
2. Are foreign currency fixed deposits in GIFT City protected by deposit insurance?
IFSC Banking Units operate under international banking guidelines managed by the IFSCA rather than the domestic Reserve Bank of India deposit insurance framework. Investors typically place fixed deposits with premier international or tier-one domestic public and private sector banks operating authorized branch units inside the zone.
3. What makes GIFT City commercial real estate yields higher than other Indian metros?
Commercial yields in GIFT City, currently ranging between eight and ten percent, are supported by corporate demand driven by ten-year tax holidays, streamlined single-window clearances, and modern infrastructure. These corporate incentives attract multinational tenants willing to sign long-term, institutional-grade leases.
4. Do non-resident investors need to file income tax returns in India if they only invest in GIFT City FDs?
If an NRI’s only Indian-sourced income consists of interest earned on foreign currency deposits placed in an authorized IFSC Banking Unit in GIFT City, that interest is exempt from domestic income tax under Section 10(4D), meaning no domestic annual return filing is triggered on account of that income.