Institutional buyers, corporate founders, and high net worth individuals evaluating real estate in India increasingly look toward Gujarat International Finance Tec-City for capital deployment. While capital appreciation often dominates headlines, seasoned investors understand that long-term asset performance depends on steady, predictable cash yields. Accurate underwriting requires looking past headline yields and analyzing the mechanics that govern day-to-day liquidity.
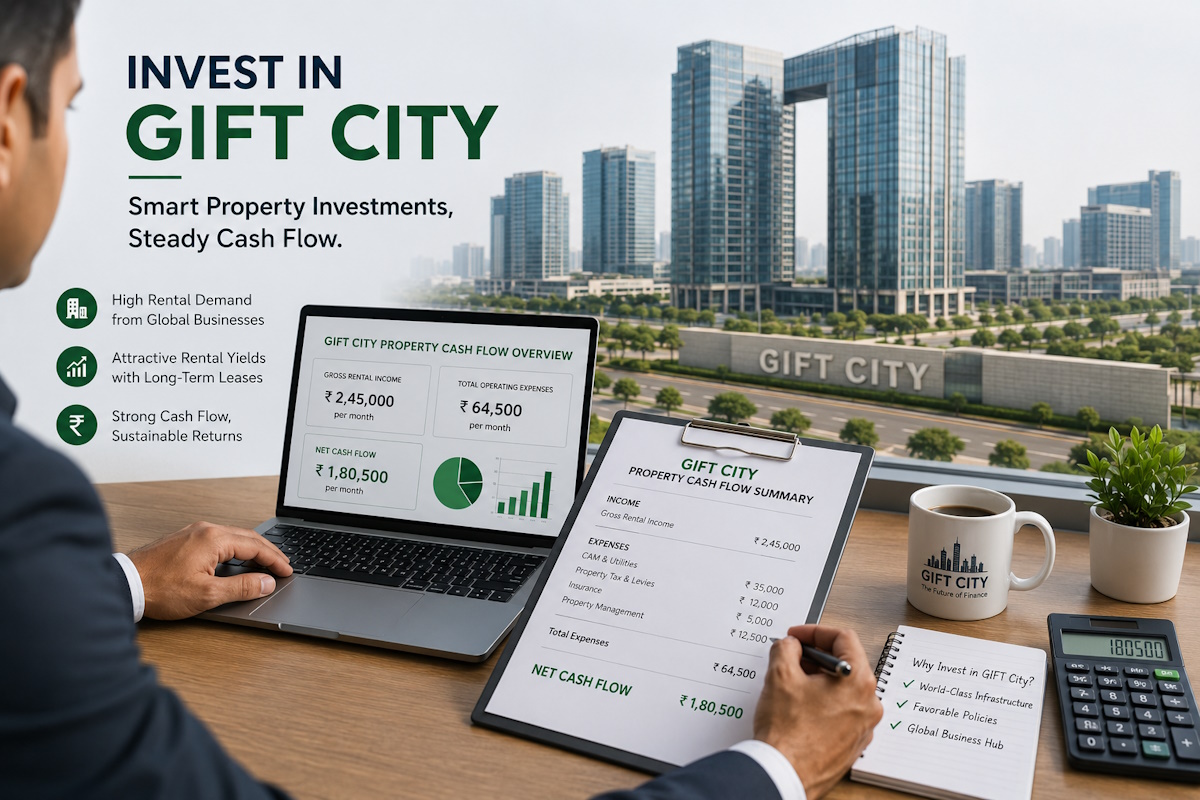
Estimating your net GIFT City property cash flow demands a granular assessment of both revenue streams and operational expenses. In a dynamic international financial services center where regulatory frameworks, Special Economic Zone (SEZ) mandates, and Domestic Tariff Area (DTA) policies intersect, broad projections can lead to costly mistakes. Establishing a reliable cash flow model upfront ensures your capital yields sustainable, risk-adjusted returns from day one.
The Foundations of GIFT City Rental Income: Gross vs. Net Realities
When underwriting commercial or residential assets, headline rental rates rarely reflect the actual liquid return deposited into an investor account. Calculating true yield begins with distinguishing between gross billings and net collectible revenue.
Understanding Revenue Mechanics in an IFSC Environment
Gross rental figures represent the contractual lease rate agreed upon between the landlord and the tenant. However, real-world returns depend on occupancy stability, rent escalation schedules, and collection efficiency. In GIFT City, commercial leases often feature structured escalation clauses, commonly 12% to 15% every three years, or 5% annually, which directly impacts multi-year cash flow projections.
Commercial SEZ vs. Non-SEZ (DTA) Cash Flow Dynamics
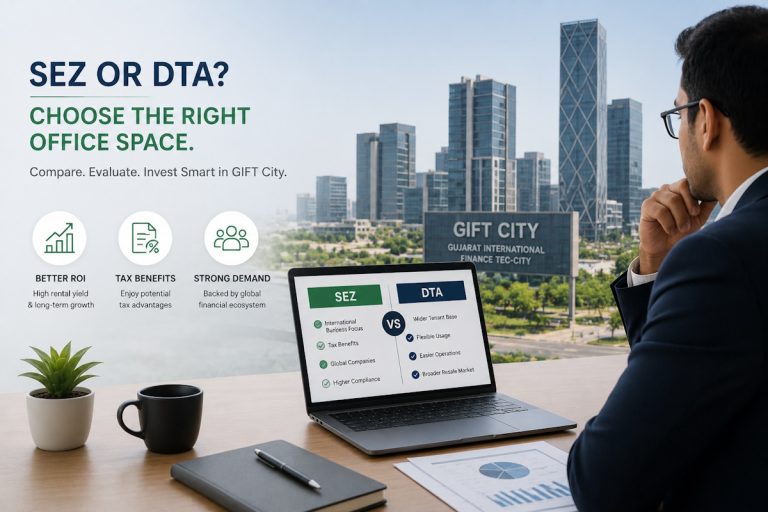
A key variable in estimating GIFT City rental income is the regulatory zone where your property sits. Processing zones within the SEZ/IFSC cater specifically to offshore banking units, international financial intermediaries, global capability centers, and alternative investment funds. Leases here are typically long-term, spanning 5 to 9 years with institutional-grade lock-in periods. In contrast, Non-SEZ or DTA properties cater to domestic businesses and support services. While DTA spaces offer faster leasing velocity and broader tenant pools, SEZ units often command higher lease stability and blue-chip corporate covenants.
Residential Leasing Drivers
On the residential side, cash flow is driven by the influx of corporate executives, fund managers, IT professionals, and expatriates relocating to the district. Walk-to-work infrastructure and social amenities heavily influence tenant retention. Strategic cash flow planning for GIFT City investors requires mapping residential unit sizes, such as 1 BHK, 2 BHK, or studio configurations, against prevailing workforce demographics to minimize friction between tenant turnover cycles.
Deconstructing the Expense Side of GIFT City Real Estate
Accurate underwriting requires an honest breakdown of recurring and non-recurring operational expenditures. Underestimating operational drag is one of the most common pitfalls for property investors entering new micro-markets.
Common Area Maintenance (CAM) and Utility Infrastructure
GIFT City features world-class utility infrastructure, including automated waste collection, district cooling systems, and dedicated utility tunnels. These high-efficiency services reduce operational downtime but come with specific operational charges. Investors must clarify whether CAM charges are passed through entirely to the tenant on a triple-net lease basis or if the landlord absorbs baseline fees during transition periods.
District Cooling System (DCS) Billing
The centralized air conditioning network removes the need for individual chiller units, lowering long-term capital expenditure for maintenance. However, understanding standard capacity charges versus active consumption billing is vital when drafting lease terms to protect your net yields.
Property Taxes and Municipal Levies
Local administration charges, property taxes, and developmental surcharges levied within the GIFT City jurisdiction must be factored into your financial model. While competitive compared to traditional metro centers like Mumbai or Bengaluru, they remain an ongoing line item that impacts the bottom line.
Asset Management and Property Sinking Funds
Passive investors, particularly NRIs and family offices based outside Gujarat, must account for third-party property management fees. Engaging professional property managers typically accounts for 5% to 8% of gross monthly collections. Additionally, allocating 1% to 2% of annual rental revenue toward a capital expenditure sinking fund ensures your unit remains competitive for incoming executive tenants.
Occupancy Variables, Fit-Out Periods, and Vacancy Drag
Even the most prime real estate experiences periods without active rent collection. Modeling these transitional gaps accurately prevents unexpected cash shortages during your investment lifecycle.
Factoring in Fit-Out Rent-Free Periods
In the commercial office sector, corporate tenants usually negotiate a rent-free fit-out period ranging from 30 to 90 days, depending on unit size and handover conditions (bare shell vs. warm shell). During this window, you maintain ownership carrying costs without incoming lease checks. Factoring this initial downtime into your year-one yield calculation is essential for realistic forecasting.
Turnover Cycles and Tenant Sourcing Timelines
Residential lease terms in India traditionally run for 11 to 24 months, while commercial leases extend much longer. Analyzing historical lease turnover helps you project realistic downtime between tenants. Understanding localized absorption patterns and evaluating vacancy risk in GIFT City enables you to stress-test your cash balance against potential two-month to four-month marketing vacancies between corporate tenancies.
Step-by-Step Property Cash Flow Calculation Framework
To establish clarity on expected returns, investors should follow a systematic formula when analyzing any potential commercial or residential asset within the zone.
1. Calculate Potential Gross Income (PGI)
Multiply the total leasable square footage by the prevailing market rent per square foot, annualized over twelve months, including contracted parking fees and signage rights where applicable.
2. Determine Effective Gross Income (EGI)
Subtract an estimated vacancy allowance (typically 5% to 8% for institutional assets) and credit loss allowances from your Potential Gross Income. This provides a realistic estimate of incoming cash.
3. Deduct Total Operating Expenses (OpEx)
Subtract routine landlord-borne costs, including property taxes, insurance, unrecovered maintenance charges, building sinking fund contributions, and asset management fees.
4. Compute Net Operating Income (NOI)
Net Operating Income (NOI = EGI – OpEx) represents the core financial health of the property before accounting for debt service and personal taxation.
5. Factor in Debt Service and Net Cash Flow
If leveraging your acquisition through commercial property loans or lease rental discounting (LRD), subtract your total annual principal and interest payments from your NOI. The remainder represents your pre-tax net cash flow.
Investors tracking long-term capitalization rates can evaluate current yields against broader benchmarks by reviewing overall GIFT City rental yield potential across various asset classes.
Taxation, Regulatory Compliance, and Repatriation Impacts
Tax structuring plays a critical role in preserving your net cash flow. Operating within an international financial hub introduces specific tax dynamics that both domestic and international investors must navigate.
TDS and Rental Income Taxation
Corporate tenants deduct Tax Deducted at Source (TDS) before remitting monthly rent payments. For domestic residents, standard income tax slabs apply to rental income, though statutory standard deductions (such as the 30% deduction under Section 24 for repair and maintenance) help buffer the taxable portion of the revenue.
NRI Repatriation and Double Tax Avoidance Agreements (DTAA)
For Non-Resident Indians, rental yields from GIFT City properties can be credited directly to NRO accounts and repatriated abroad via standard Form 15CA and 15CB clearances up to current statutory limits. Utilizing applicable DTAA provisions prevents double taxation in your home country of residence, preserving net capital efficiency.
Goods and Services Tax (GST) Application
Commercial leasing is subject to GST at prevailing statutory rates, which is generally billed to and recovered from registered corporate tenants who utilize input tax credits. Residential properties leased to non-registered individuals for personal residential use generally sit outside standard commercial GST mechanics, simplifying personal accounting.
Commercial vs. Residential: Cash Flow Comparison for Investors
Choosing between commercial office space and residential housing in GIFT City depends on your capital volume, liquidity expectations, and management preferences.
Commercial Office Assets
- Yield Profile: Typically offers higher gross capitalization rates, historically ranging between 7% and 9%.
- Lease Duration: Long-term corporate commitments (3 to 9 years) with institutional lock-in periods.
- Expense Structure: Frequently structured as triple-net or modified gross leases, passing maintenance burdens to tenants.
- Entry Barrier: Higher capital ticket size, tailored to corporate investors, HNIs, and syndicated funds.
Residential Apartments and Serviced Residences
- Yield Profile: Typically ranges between 4% and 6% gross rental yield, with higher liquidity.
- Lease Duration: Shorter lease terms (1 to 2 years), allowing faster upward rent adjustments during high-demand cycles.
- Expense Structure: Landlords generally absorb minor recurring maintenance, turnover refurbishment, and routine upkeep.
- Entry Barrier: Accessible ticket size, straightforward resale market, and high individual tenant demand.
Strategic Underwriting: Making the Final Investment Decision
Underwriting real estate cash flow GIFT City projects requires disciplined valuation models rather than reliance on promotional sales brochures. The market is maturing rapidly, transitioning from early construction phases to an active financial and business ecosystem. Gift City Realty assists investors in stress-testing pro-forma financials against localized ground data, lease comparables, and tenant absorption trends.
Before deploying capital, evaluate whether an asset matches your investment timeline. If consistent cash distributions and institutional tenant profiles fit your thesis, pre-leased commercial assets or high-end residential spaces near business hubs provide the strongest stability. Always audit the developer track record, occupancy certification timelines, and exact zone demarcation before executing sales agreements.
Frequently Asked Questions
1. What is the average rental yield for commercial properties in GIFT City?
Commercial properties in GIFT City typically yield between 7% and 9% gross annually, depending on whether the asset is in the SEZ or DTA zone, building specifications, tenant covenant quality, and lease structure.
2. How are operational expenses like District Cooling charged to property owners?
District Cooling System (DCS) costs usually comprise a fixed capacity charge and a variable consumption charge. In most commercial leases, these costs are passed directly to the tenant as part of monthly utility billing.
3. Can NRIs easily repatriate rental income earned from GIFT City real estate?
Yes. NRIs can deposit rental income into an NRO bank account and repatriate funds up to USD 1 million per financial year after paying applicable Indian taxes and obtaining standard Form 15CA/15CB certifications from a Chartered Accountant.
4. How does property cash flow calculation differ between SEZ and DTA units?
SEZ units cater strictly to eligible IFSC-registered entities, leading to longer corporate leases and lower default risks, while DTA units offer a broader tenant market, faster initial leasing, but potentially more frequent tenant turnover.
5. What common mistakes should investors avoid when estimating GIFT City rental income?
Common mistakes include ignoring rent-free fit-out downtime, failing to budget for property management and sinking funds, miscalculating CAM pass-through terms, and relying on gross rather than net operating income calculations.